Practitioners May Have to Deal with New Questions About Taxpayer Alien Status on Draft 1040
The draft 2026 Form 1040 includes new questions about taxpayers’ citizenship, immigration and work authorization status. The changes could create compliance and due diligence challenges for taxpayers and practitioners.
By William R. Stromsem, CPA, J.D., George Washington University School of Business
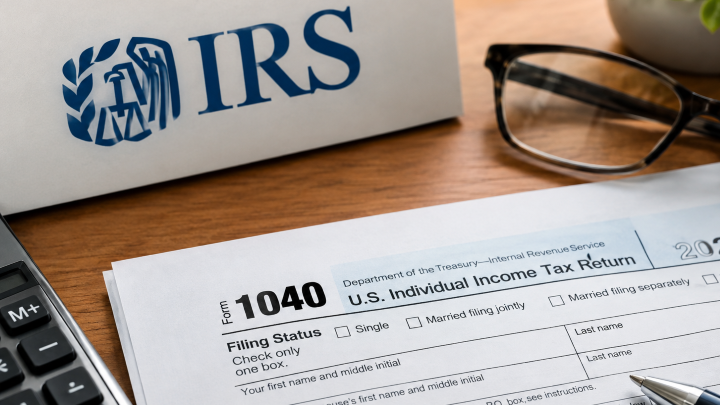
The IRS has released a draft of the 2026 Form 1040 for the upcoming filing season that includes two questions about the taxpayer's citizenship/alien status. At the top of the form, under “Filing Status” is a new section labeled “Other Information,” with two questions on the status of the taxpayer:
- If treating a nonresident alien or dual status alien spouse as a U.S. resident for the entire tax year, check the box and enter the name (attach statement if required).
- At the time you file your return, are you and your spouse if filing jointly, a U.S. citizen, U.S. national, or an alien lawfully authorized to work in the U.S.? (see instructions [note: not yet available]). (Boxes are provided to check “yes” or “no” for the taxpayer and spouse.)
The purpose seems to be to help ensure taxes are correctly assessed, including any claimed refundable or other credits intended for citizens and resident aliens. These credits are often an important source of funds for immigrant families.
Problems for Immigrant Taxpayers
The new questions can put some taxpayers in a difficult position. Basically, they must state, under potential perjury penalties, that they are citizens or are authorized to work in the U.S. Most of our clients are citizens and for them, this is not an issue - they just have to check the box. However, those with immigration issues may be reluctant to disclose this information on a government form. But not checking a box could result in an incomplete return, with a follow-up from the IRS asking that the questions be answered or the IRS not accepting the form as incomplete, with late-filing penalties. Tax compliance is an issue for those individuals who want a path to citizenship, with the citizenship application wanting to know that the applicant has paid required taxes.
There may be some confusion for immigrants who base their resident alien status on the substantial presence test, which requires that they were in the country for a specific period of time. Substantial presence would be insufficient for answering the question on the form that asks, “whether an alien is authorized to work in the U.S.” and this would generally require a Permanent Resident Card (Green Card).
Problems for Practitioners
If the draft form is finalized, following are some issues that the practitioner may have to address.
1. Clients with immigration issues may view the CPA as an adverse party and we will have to work with them to try to encourage tax compliance. We may need to reassure them that this information is for collecting taxes, not for immigration purposes, but they may suspect cooperation between the agencies, possibly with good reason, in the future.
2. We cannot sign an incomplete return if the taxpayer refuses to check the boxes. Signing an incomplete return could result in a Section 6694 (a) penalty for failure to follow IRS rules and regulations, which by definition include following IRS forms and instructions.
3. We must consider our responsibility for the correctness of the status claimed. Generally, we can accept information provided by clients and are not required to audit the facts. However, we must have a good faith belief that the information is correct and if the information seems incorrect, incomplete or contradictory, we may have a duty to inquire further under Circular 230 (Section 10.22 requires due diligence and Section 10.34 states that practitioners can rely on client information without verification), SSTS No. 3, and Treasury Regulations for Section 6694. Failing to probe obvious inconsistencies can trigger preparer penalties under IRC Section 6694. Also, the IRS may establish a due diligence penalty similar to the requirement to view a Social Security card or ITIN when signing a return with a dependent for the Earned Income Credit or Head of Household filing status, requiring us to view proof of claimed immigration status (e.g., a Green Card). To avoid penalties, practitioners may wish to document the basis for their good-faith belief in the correctness of the claimed alien status.
We will follow developments and keep you informed.
Topics: