November 10, 2023

Special-Purpose Acquisition Companies Growing More Popular But Present Unique Accounting Issues
The use of special-purpose acquisition companies (SPACs), also known as blank check companies, has increased exponentially over the past few years. They allow investors to take companies public without the costs and delays associated with traditional IPOs. A SPAC is created to pool investor funds to accomplish a merger or acquisition within a specified period of time. At creation, the acquisition target is generally not known to the investors. Since 2020, more than half of U.S. IPOs have utilized the SPAC structure.

Before we discuss the typical SPAC structure, let’s examine the advantages it offers over the traditional IPO. The SPAC is registered with the SEC and is a publicly traded company. As such, the public can buy its shares; hence the nickname “poor man’s private equity fund.” The SPAC can typically go public in just a few months, shortening the time typically required for a conventional IPO of six months to more than a year. However, it lacks an active business since the acquisition of a target has not been completed.

Given the simplicity of the SPAC balance sheet, preparation for going public is both quicker and less expensive. This is not to say that the costs associated with taking the target company public are avoided fully. Financial information of the target is generally required to be presented to the SPAC investors to receive final approval of the transaction and the target must be “public ready” upon completion of the merger.

A SPAC transaction generally follows a well-established path:

  • Units comprised of Class A shares and some fraction of a warrant are sold to investors for $10 upon the SPAC going public. This will generally compose about 80% of the share capital.
  • The sponsors are awarded founder shares and warrants for a nominal investment to make up the remaining 20% of the share capital.
  • The proceeds are held in trust to be used for the acquisition of a target within a limited time frame; usually less than 24 months.

If the acquisition is not completed within the window, the investors’ shares are redeemed (plus interest) from the funds in trust. However, the sponsors can generally induce the investors to extend the acquisition deadline by making a contribution to the trust fund.

Investors can sell their shares and/or warrants on the secondary market at any time. Sponsors are generally required to retain their shares and warrants.

Once a target is identified and the merger is pending, investors can opt out by demanding redemption of their shares. They can retain the warrants even if the shares are redeemed. For those who participate on the initial offering of the SPAC shares, they are therefore guaranteed the return of their initial investment. Investors buying the shares on the secondary market receive no warrants and pay market price.

The warrants (typically with a strike price of $11.50) generally have a term of five years from the date of the acquisition. The SPAC may call the warrants if their trading price for a period of days (usually 20 -30) exceeds a stated price, which is generally $18. This call feature basically forces holders to exercise the warrants. Sponsor warrants do not include the call feature. The public warrants can only be exercised for cash while the sponsor warrants may be for cash or shares.

Investors should be aware that their shares will typically be diluted. The sponsor shares are awarded without cash investment, which results in dilution of the investor shares of up to 20%. Redemption of Class A shares from investors who opt out prior to the merger can typically run as high as 40 – 50%. Therefore, at merger, only 40% of the share capital may actually be fully cash funded. If the price of the shares rises, the warrants are then likely to be exercised at the $11.50 strike price, further diluting the return of the initial investors.

Recent SEC scrutiny of the warrant accounting has resulted in restatements by several SPACs. Many SPACs had concluded that the warrants should be classified as equity. However, to be classified as equity, the company must evaluate the instrument under a two-step process: (1) the contingent exercise provisions and (2) the settlement options. And it is the latter that has prompted the SEC to disagree with the conclusions of the reporting entities.

To qualify as equity, the settlement must be a “fixed-for-fixed” calculation with the exception that any adjustments are based on standard inputs used to determine the value of “fixed-for-fixed” equity forwards or options. The sponsor options are not redeemable and therefore fail the exception since “type of holder” is not a standard input.

The public warrants often fail the exceptions since the SPAC fails to control the ability to settle with shares. This failure is based on the provision in most SPAC warrant agreements that allows the holders to elect to receive cash in the event of a tender or exchange of the underlaying shares in the context of a change of control.

SPACs failing the exceptions have been required to restate their financials classifying the warrants as derivatives in the liability section of the balance sheet, which requires revaluation at every report date. By the time a restatement is identified, the acquisition of the target has likely been completed, making the restatement an event of note to the investors.

Recently, there has been an increase in the number of SPACs opting to liquidate rather than close acquisitions. Given the complexities of the unique structures of SPACs and the SEC’s accounting treatment evaluation, only time will tell if they remain popular acquisition vehicles.
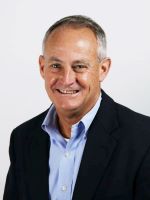
Don Carpenter, MSAcc/CPA

About the Author: Don Carpenter, MSAcc/CPA, is clinical professor of accounting at Baylor University. Contact him at Don_Carpenter@baylor.edu.


  • Workforce Development

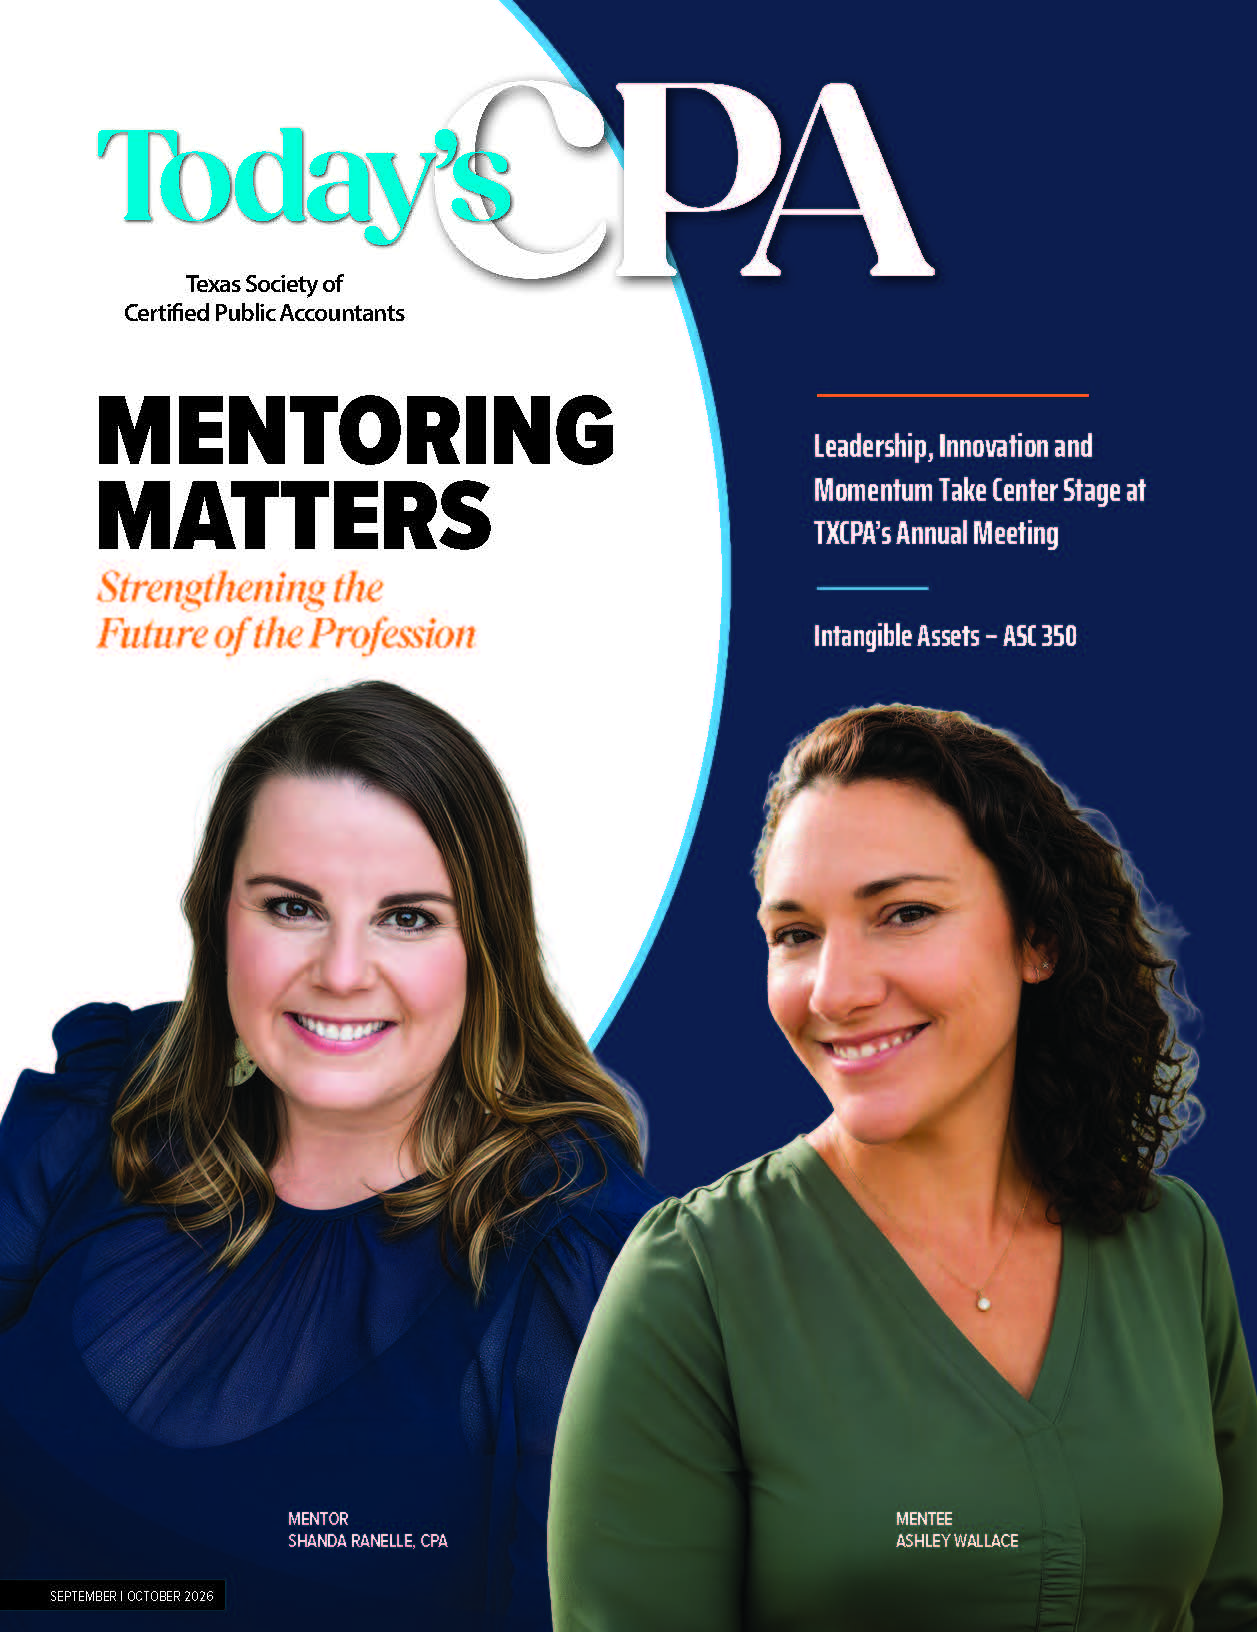
    Mentoring Matters: Strengthening the Future of the Profession

    Mentoring is a cornerstone of the accounting profession. From supporting students and CPA candidates to accelerating the growth of experienced professionals, mentoring strengthens confidence, preserves institutional knowledge and prepares future leaders. TXCPA's Mentor Match program is designed to help members build meaningful professional relationships that support their career growth and development.
    View Article
  • CPE: Intangible Assets – ASC 350

    FASB’s recent targeted GAAP improvements address the accounting and reporting of internally developed software. ASU 2025‑06 replaces development‑stage rules for internal‑use software with a “probable‑to‑complete” capitalization threshold.
    View Article
    IPR&D
  • volunteer leadership

    Leadership, Innovation and Momentum Take Center Stage at TXCPA's Annual Meeting

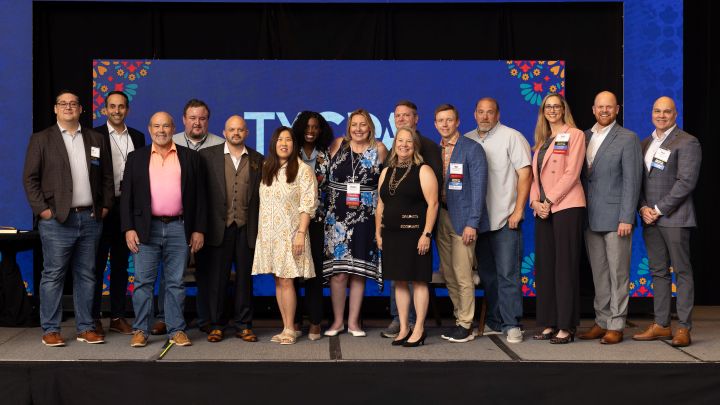
    TXCPA’s 2026 Annual Meeting brought more than 200 leaders together to celebrate organizational achievements, discuss emerging trends and shape the future of the organization. As the organization enters the final year of its Strategic Plan, the meeting emphasized momentum, collaboration and continued involvement in TXCPA and the accounting profession.
    View Article
  • Expanding the CPA Pipeline: An Important Joint Initiative for CPA Firms and K-12 Schools

    CPA firms, universities and professional organizations are using coordinated efforts to expand the future CPA talent pipeline by reaching students much earlier in the K‑12 system. Because many students choose career pathways as early as 8th grade, the authors emphasize shifting outreach toward freshmen and sophomores already inclined toward business studies.
    View Article
    TXCPA Accounting Opportunities Month
  • Workforce Development

    Mentorship, Momentum and the Future of the Profession

    Strong connections are essential to the future of the CPA profession. This CEO's Message highlights the power of mentorship, TXCPA’s efforts to strengthen the accounting pipeline, and the many ways members, volunteers and chapters are helping build opportunities for the next generation of CPAs.
    View Article
  • Outstanding Chapter Awards Recognize Achievements in Leadership and Service

    TXCPA’s Outstanding Chapter Awards recognize small and medium-sized chapters for excellence in leadership, member service, innovation and community involvement. The 2025-26 recipients, TXCPA Rio Grande Valley and TXCPA East Texas, were honored for their strong student outreach initiatives, professional development opportunities, scholarship fundraising, member engagement and community service.
    View Article
    volunteer leadership
  • Workforce Development

    Beyond Tax and Audit: Shedding Light on Alternative Career Pathways

    Accounting offers far more career opportunities than traditional tax, audit and financial reporting roles. By introducing students to the diverse ways accounting skills can be applied, educators and practitioners can help the next generation of CPAs see the many possibilities an accounting career can offer.
    View Article
  • What’s Happening Around Texas - September-October 2026

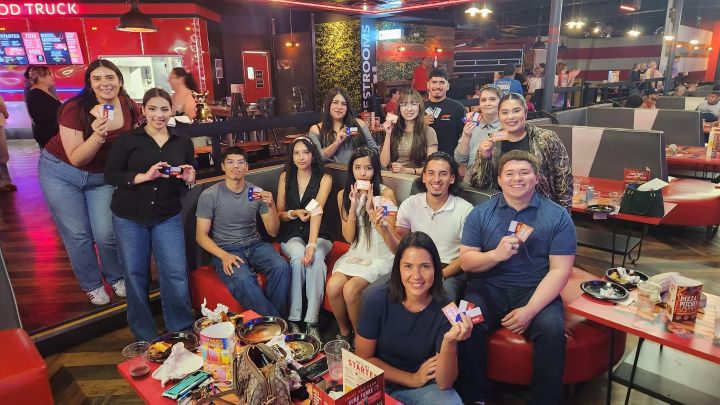
    TXCPA chapters across Texas are strengthening connections through student engagement events, legislative conversations, member appreciation gatherings, and strategic planning sessions. From Corpus Christi’s student bowling mixer and to Southeast Texas’ celebration with Lamar University to El Paso's and San Antonio’s focused planning meetings and Victoria’s community‑building event, each chapter is fostering momentum, collaboration and professional growth.
    View Article
    TXCPA Chapters
  • Tenure

    Is Accounting Academia Still a Good Career Option for CPAs? An Updated Perspective

    Is accounting academia still an attractive career path for CPAs? Although demand for accounting Ph.D. graduates has declined despite earlier predictions of faculty shortages, accounting professors continue to enjoy strong compensation, work/life balance, tenure stability and summer flexibility.
    View Article
  • Spotlight Article: Leading Beyond the Numbers

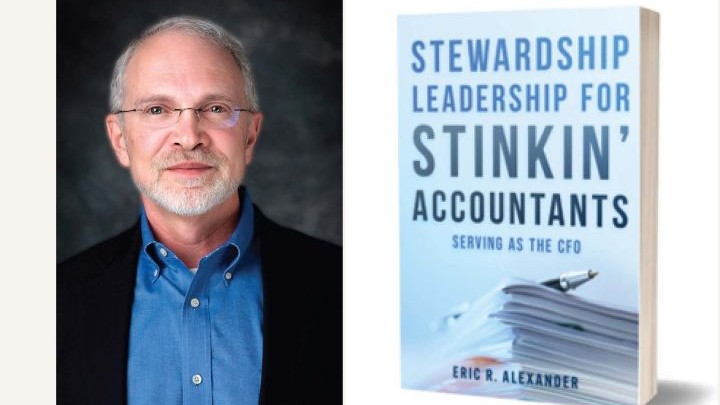
    Eric R. Alexander discusses the lessons behind his book “Stewardship Leadership for Stinkin' Accountants: Serving as the CFO” and how a servant mindset, wisdom and relationships create a lasting impact. He explores why trust, accountability and communication are essential to effective financial leadership, especially as AI transforms the profession.
    View Article
    Strategic Planning
  • Sustainability reporting

    Assessing Materiality of ESG Risks: Guidance for CPAs

    This article explains how CPAs can assess and disclose material environmental, social and governance (ESG) risks that may affect a company’s financial position, operations and stakeholders. The concept of double materiality is introduced, which considers both the financial impact of ESG risks on a company and the company’s impact on society and the environment.
    View Article
  • PCC Addresses Priority Private Company Issues in Q2

    This update summarizes the Private Company Council (PCC) activities for the second quarter of 2026. During its June meeting, the council prioritized improving financial disclosures for Employee Stock Ownership Plans (ESOPs) and targeted lease accounting simplifications for private companies, and discussed FASB's decision to add a project on subjective acceleration clauses and debt default disclosures.
    View Article
    Private Company Council
  • volunteer leadership

    Leading the Way: TXCPA Thanks Our 2026-2027 Faculty and Student Ambassadors

    TXCPA celebrates and thanks our 2026–2027 Faculty and Student Ambassadors, whose leadership and enthusiasm bring our programs, resources and opportunities directly to campuses across Texas. Their commitment strengthens our connection to future professionals and fuels the growth of the CPA pipeline statewide.
    View Article
  • Profitable Is Not the Same as Valuable

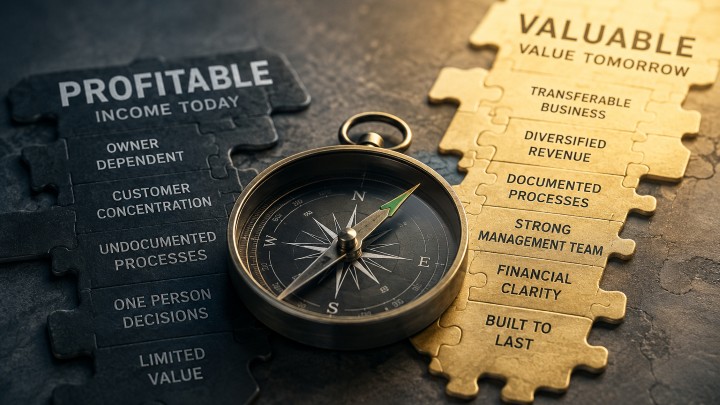
    A profitable business is not necessarily a valuable or transferable one, as enterprise value depends on organizational architecture rather than dependence on the owner’s involvement. The central message: profitable operations generate income, but only well‑structured businesses build equity that can be sold, transferred or relied upon for retirement.
    View Article
    valuation
  • Workforce Development

    A New Era for CPA Licensure in Texas – and a Look Ahead

    Texas has entered a new phase of CPA licensure with the implementation of Senate Bill 262 on August 1, 2026, creating an alternative pathway that allows candidates to qualify with 120 hours of education and two years of experience, alongside the traditional 150‑hour route. As the 2027 legislative session approaches, TXCPA is preparing to protect strong licensing standards, monitor deregulation efforts and engage newly elected lawmakers.
    View Article
  • Take Note

    In this edition of Take Note: A Legacy of Mentorship - A Tribute to John Baines, CPA-Dallas; Accountants Confidential Assistance Network (ACAN); CGMA® Designation; TXCPA Member Insurance
    View Article
    TXCPA Member Insurance
  • Virtual Accounting

    Classifieds

    The Classifieds section of Today's CPA provides a one-stop destination to find practices for sale, connect with buyers, and access services that support growth, transition and market expansion.
    View Article
  • Download Full September-October 2026 Issue (PDF)

    View Article


CHAIR
Angela Ragan, CPA

PRESIDENT/CEO
Jodi Ann Ray, CAE, CCE, IOM

CHIEF OPERATING OFFICER
Melinda Bentley, CAE

EDITORIAL BOARD CHAIR
Derrick Bonyuet-Lee CPA, CGMA

MANAGER, MARKETING AND COMMUNICATIONS
Peggy Foley
pfoley@tx.cpa

MANAGING EDITOR
DeLynn Deakins
ddeakins@tx.cpa

CLASSIFIEDS
DeLynn Deakins
ddeakins@tx.cpa

Texas Society of CPAs
14131 Midway Rd., Suite 850
Addison, TX 75001
972-687-8550


EDITORIAL BOARD
Derrick Bonyuet-Lee, CPA-Austin;
Drew Chumley, CPA-Fort Worth;
Adam Dimmick, CPA-Houston;
Julia Frink, CPA-Fort Worth;
Baria Jaroudi, CPA-Houston;
Jeffrey Johanns, CPA-Austin;
Brian Johnson, CPA-Central Texas;
Michael Kraten, CPA-Houston;
Lucas LaChance, CPA-Dallas;
Shilpa Boggram Sathyamurthy, CPA-Houston.

CONTRIBUTORS
Melinda Bentley; Kenneth Besserman; Holly McCauley; Shicoyia Morgan; Craig Nauta; Triniti Patterson


10:00 Acting as Manage