November 13, 2023
Cannabis Business: Risks and Mitigating Actions for CPAs
According to BDSA Analytics, a research agency in the cannabis (aka marijuana) industry, the U.S. cannabinoid market is projected to grow to $42.2 billion by 2026, which represents an 11% growth rate. Many mature markets in the U.S. have experienced accelerated growth rates and more markets may soon become available. Still, even with such an impressive outlook, not many CPAs provide services to this industry. This article discusses the risks practitioners may face and what actions can be taken as they explore this industry.
The Controlled Substances Act (CSA) regulates the manufacture, importation, possession, use, and distribution of controlled substances. Depending on certain factors, such as potential for drug abuse or dependency, drugs are classified into five categories, with marijuana falling into Schedule 1 along with heroin and ecstasy, which represent the highest category for potential abuse (https://www.dea.gov/drug-information/drug-scheduling).
Despite this federal restriction, many states have legalized the use of marijuana for medical purposes and even for recreational purposes. Starting with California in 1996, there are now 33 states (and the District of Columbia) that have enacted laws making medical cannabis legal and 11 (plus the District of Columbia) that have legalized its sale for recreational use (Owens-Ott, Snyder, & Ott, 2022). The conflict between federal and state laws regarding the legality of the cannabis business has created significant challenges and risks that practitioners must be aware of before providing services in this industry.
Risk for CPAs
First and foremost, the cultivation, distribution and use of cannabis is a federal crime under the Controlled Substances Act. Therefore, CPAs can be prosecuted and accused of promoting and facilitating an illegal federal business. Although no accountant working with state-licensed cannabis businesses has yet been prosecuted by the federal government, practitioners must be aware the risk still exists as they are collecting fees from a “criminal” enterprise according to federal law.
Furthermore, practitioners must be aware that even though cannabis may be legal in some states, there may be a few municipalities that have not sanctioned this business. As a result, CPAs must know which cities and counties in which the cannabis business has been legalized (Saylor, 2021).
Given the severity of issues that may arise due to the distinctions between federal and state laws, many practitioners may turn to their insurance carriers. However, CPAs cannot fully rely on their professional liability insurance, as most policies do not cover criminal investigations and the related penalties that may be imposed by licensing and legal authorities.
Even if policies provide protection for claims of negligence, practitioners must be aware of policy restrictions and therefore, terms and conditions must be closely reviewed. For instance, coverage is typically excluded if claims include allegations that the firm or individuals employed by the firm engaged in dishonest, fraudulent or criminal acts. Policy exclusions may include exceptions, which may not apply if a court finds the insured party guilty of the allegation (Sterna and Wolfe, 2017).
In 2015, AICPA issued a white paper, “An Issue Brief on State Marijuana Laws and the CPA Profession,” which indicated state boards of accountancy could consider providing services to a cannabis business as an argument to deny an application to grant or renew a CPA license. This could be based on a failure to show good moral character or as justification for disciplinary action. Furthermore, it adds that practitioners who have provided services to a cannabis business may face issues when seeking a reciprocal license in another state where marijuana is illegal. It also claims services to a cannabis business, even if legal within a state, might be considered a discreditable act by a state board due to a violation of federal laws.
Lack of good moral character can constitute grounds to lose a CPA license. As this “good moral character” requirement is not consistently defined, Jerry Hill, General Counsel for the Texas State Board of Public Accountancy, was contacted to obtain the State Board’s position. In response to this issue, Jerry asserted:
“It is exclusively the jurisdiction of state and federal courts to determine if, and when, drug laws are violated. In the absence of such a determination by the courts, the Texas State Board of Public Accountancy will not pursue independent disciplinary action against a Texas CPA or CPA firm operating within the boundaries of Texas or federal law.
In line with the above statement, there would be no violation of this agency’s rules for a Texas CPA to provide accounting services to a provider of marijuana in a state where the sale of marijuana is lawful. Laws and enforcement policies can change, however, and a licensee must be diligent in knowing applicable laws and policies.”
While the above statement may seem a relief for many practitioners, it can be noted it acknowledges that a determination is subject to state and federal courts. Since cannabis is illegal under federal law, the controversy continues.
The accounting profession delivers services that are often driven by relationships. As cannabis businesses are not only illegal but perceived with some stigma, practitioners may have their professional reputation suffer as some stakeholders (e.g., prospective clients) in their communities do not support this activity.
In their research, Owens-Ott, Snyder & Ott (2022) found reputational risk a common theme listed as another potential risk. CPAs must continue to be aware that a “guilt by association” can destroy their reputation (Werner & Will, 2019). Practitioners must also assess their level of comfort regarding moral and ethical values when providing services to a cannabis business.
Practitioners serving the cannabis business will encounter several risks that are unique to this industry. First, few banks provide services as they may also face the risk of prosecution. This is true as financial institutions must exercise a higher level of scrutiny to comply with the Anti-Money Laundering (AML) and Bank Secrecy Act (BSA). Therefore, many cannabis businesses work on a cash-basis resulting in a high volume of cash transactions, which in turn may result in higher risk of theft and fraud. As a result, cash reconciliation and review should be performed (Saylor, 2021).
Secondly, given the nature of the inventory, businesses will be highly susceptible to thefts. More importantly, how can accountants obtain some level of assurance of the quality and value of the product being produced? As many cannabis businesses rely on a fair value model, asset valuation based on current market values could become complicated as practitioners will need to determine the value of the plant while it is growing, before it can be sold. Numerous factors, such as weather conditions, insects or other pathogens, could ultimately impact the value of the cannabis business (Silverstone & Wickersham, 2020).
Because marijuana is classified as a Schedule 1 controlled substance under federal law, cannabis businesses are subject to Section 280E of the Internal Revenue Code. Taxpayers are then faced with a major dichotomy as all income, regardless of whether it was obtained legally or illegally, must be reported. However, Section 280E disallows expenses related to an illegal enterprise. In other words, “ordinary and necessary” business expenses are disallowed and instead, only expenses related to “return of capital” (e.g., the cost of seeds, seedlings and growing lights) can be deducted.
Effectively, the federal income tax liability is calculated based on gross income rather than net income (Hopkins, 2022). Compliance with Section 280E results in a greater level of complexity that requires practitioners to be well-educated regarding the proper accounting procedures and implementation of adequate internal controls to safeguard assets, including cash and inventory.
The complexity created by Section 280E may also result in a higher likelihood of being audited by the IRS. The high volume of cash transactions previously mentioned along with the lack of an adequate paper trail creates the perfect environment for tax evasion (Owens-Ott, 2020).
Due to the issues listed above, Dempsey & Cacanando (2022) argue a cannabis business may have a difficult time obtaining funding in the absence of adequate internal controls around processes, such as cash and inventory management. A going concern risk emerges as these issues compound, which impact the business’s ability to operate successfully, navigating both federal and state laws. CPAs must evaluate management’s plans and include any concerns in their reports.
A more technical issue relates to knowing the actual product, cannabis and its derivatives: marijuana and hemp. In the U.S., the level of THC (e.g., tetrahydrocannabinol), the substance containing psychoactive properties, defines the difference between agricultural grade hemp and marijuana. Hemp is defined as any substance containing less than 0.3% of THC and it is federally legal since the passage of the Agricultural Improvement Act of 2018. Any plant exceeding 0.3% THC limit is considered marijuana and remains illegal under the Controlled Substances Act (Saylor, 2021).
However, psychoactive components of the cannabis plant can be natural or synthetically derived. Accordingly, the Drug Enforcement Agency (DEA) issued a clarification (Beneduce, 2023) that products with synthetically derived cannabinoids are federally illegal as schedule 1 drugs. To add to the confusion, it has been reported U.S. hemp farmers are growing hemp to produce cannabinoids, such as CBD, which is similar to marijuana (Quinton, 2020).
This confusion may result in further delays to ease any discrepancies between federal and state laws and, a higher level of complexity that practitioners must be ready to assess if serving this industry.
How to Mitigate the Risk
Given the high level of risk inherent in the cannabis business, practitioners are strongly advised to conduct comprehensive due diligence, including:
- Meet principals of prospective clients face-to-face to assess their character and level of integrity. Also, conduct background checks on all workers.
- Require clients to maintain ongoing legal representation. Obtain their consent to meet periodically with their lawyers to ensure a full understanding of current federal, state and local laws impacting the cannabis business.
- Retain annual written engagement letters with detailed descriptions of the scope of the services, including provisions where clients assert their business is operating legally under applicable state laws, indemnification clauses in case of management misrepresentation, and copies of their current business licenses.
- Reach out to insurance carriers to understand what services can be performed and determine best-in-class risk management for the cannabis industry.
- Maintain strong quality control procedures when accepting clients so any business with deficient cash and inventory management processes can be identified promptly. By doing so, risk can be timely assessed and, if needed, additional training on business controls and fraud prevention procedures can be proactively launched.
- Keep current with the education and work experience requirements by taking the necessary training and staying alert to the positions of the various state boards of accountancy and IRS rulings. Also, gain a broad understanding of the cannabis industry by a.) subscribing to industry publications, b.) attending events from trade associations and local chambers of commerce, and c.) monitoring social media sites to identify players and current issues impacting the industry.
Due Diligence and Client Acceptance
More states will likely continue to legalize and regulate use of cannabis and if regulated, the State of Texas would represent the second largest addressable market in terms of population (Stahura, 2022). With the projected growth rates, practitioners should pay attention to expanding their practices into this emerging industry. Before doing so, however, practitioners must be ready to conduct comprehensive due diligence and client acceptance and retention procedures to minimize the risks associated with this industry.
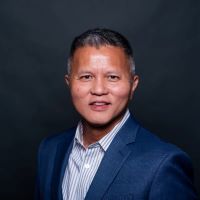 About the Author: Derrick Bonyuet, Ph.D., CPA, CFA, CFP, is a Clinical Assistant Professor in the Accounting Department at the Texas McCombs School of Business.
References
Amason, Allen, and Schweiger, David. “The effects of conflict on strategic decision-making effectiveness and organizational performance.” Using conflict in organizations (1997). Sage Publications.
AICPA. “An issue brief on state marijuana laws and the CPA profession.” (2019).
Beneduce, William. “Delta-what??!! Delta-8 and Delta-9 create high anxiety for policymakers. National Law Review (2023).
DEA United States Drug Enforcement Administration. “Drug Scheduling.”
Dempsey, Mike, and Cacanando, Alex. “Capitalizing on risks and returns: Risk management considerations for cannabis banking.” (2022).
Owens-Otto, GS. “Accounting and the US cannabis industry: Federal financial regulations and the perspectives of Certified Public Accountants and cannabis businesses owners.” Journal of Cannabis Research (2020). DOI: 10.1186/s42238-020-00049-7.
Quinton, Sophie. “Cannabis confusion pushes states to ban smokable hemp.” (2020).
Saylor, Teri. “Serving cannabis clients: Understand the risks.” Journal of Accountancy (2021).
Silverstone, Howard, and Wickersham, M. “Cannabis industry holds unique challenges for CPAs.” (2020).
Stahura, Elisabeth. “Mining for gold: BDSA market outlook, key insights, and ways to win.” (2022).
Sterna, Stanley, and Wolfe, Joseph. “Liability risks and other concerns when servicing marijuana businesses.” The CPA Journal (2017).
Werner, Randy, and Will, Duncan. “Managing the risks of serving cannabis clients.” (2019).