SEC Approves Nasdaq’s Proposals for Board Diversity Disclosure
DOWNLOAD PDF


Accounting & Auditing

By By Don Carpenter, MSAcc/CPA

Nasdaq’s proposals regarding increased disclosures on board diversity have received SEC approval. The new requirements are intended to address the continued lack of female and underrepresented minority board representation when compared to the population in general.

The first proposal will require a Nasdaq-listed company to have (or explain why it does not have) at least two diverse members. One of the members should self-identify as a female and one as an underrepresented minority or LGBTQ+. If the company does not meet the targets, it must provide the diversity requirements to a reader and then explain why it did not satisfy them.

Nasdaq allows broad discretion with regard to meeting the explanation requirement. It offered examples of explanations, such as:

  • The company does not believe Nasdaq’s listing rule is appropriate.
  • The company does not believe achieving Nasdaq’s diversity objectives are feasible given the company’s current circumstance.
  • The company is committed to ensuring that the Board’s composition appropriately reflects the current and anticipated needs of the Board and the company.”

The disclosure in lieu of compliance is required to be made annually in either the proxy statement (or an information statement if the company does not file a proxy) or on the company’s website. If the company elects to satisfy the requirement via the website, it must do so concurrently with the filing of the proxy statement and provide the link through the Nasdaq Listing Center.

If a company has five or fewer board members, it can meet compliance with only one board member who meets the diversity definitions. If it adds a sixth member to comply, it will continue to satisfy the requirement without being required to meet the “two diverse member” requirement of larger boards. But expanding to seven board seats would require a second diverse representative.

Smaller reporting companies (as defined in Rule 12b-2) are allowed to avoid the explanation disclosure with two diverse board members, but both members may be female. It is not required to have one of the two members be either an underrepresented minority or LGBTQ+.

In addition, Nasdaq-listed companies are required to report annually a “Board Diversity Matrix” that provides the total number of directors and:

  • The number who identify as female, male, non-binary or do not disclose gender;
  • The number who identify by race and ethnicity; and
  • The number who identify as LGBTQ+.

The matrix must be provided annually in the same manner as the company’s explanation for not meeting the diversity criteria (proxy or website). After the first year, the report must include the current and prior year matrix. The matrix must be provided in a searchable format.

Non-compliant companies will have 45 days to submit a plan to comply after receiving failure notification and those that fail to comply within 180 days will receive a Staff Delisting Determination. Compliant companies that fall out of compliance due to a board vacancy will have one year from the later of the date of vacancy or the filing of the next proxy statement to meet the requirements.

Companies must comply by the later of August 7, 2023, or the date the company files its proxy for the 2023 annual shareholders’ meeting. Smaller companies have extended compliance dates. Nasdaq Global Select Market and Nasdaq Global Market companies have until 2025 and Nasdaq Capital Market companies have until 2026.

The diversity matrix requirement becomes effective on the later of August 8, 2022, or the filing of the proxy statement for the 2022 shareholders’ meeting, if later.

In conjunction with the diversity disclosure proposal, a second proposal will offer eligible companies a year of access to a board recruiting service to identify and evaluate board-ready diverse candidates. Eligible companies are those that (1) lack at least one director who self-identifies as female and (2) at least one director who self-identifies as an underrepresented minority or LGBTQ+.

Critics have been quick to argue that the requirements run afoul of the equal protection provisions of the 14th amendment to the U.S. Constitution and various civil rights laws. Others have commented that the proposal was “designed to address political and social issues and would redefine the purpose of businesses.”

If accepted, these positions argue that Nasdaq has exceeded its authority and that the requirements are therefore unlawful. The proposal will almost certainly be challenged in court consistent with earlier board diversity regulations enacted by the state of California.

Nasdaq’s counter to these arguments is that the rules are not diversity quotas or mandates, but only disclosure requirements that are intended to give investors greater insight into a company’s approach regarding board diversity. Under the proposal, a company is not compelled to meet the diversity goals, only disclose its rationale for not complying with them.

It will be interesting to monitor these new requirements as the reporting deadlines near. Additional research may be needed to determine the extent to which investors rely on the data when they are making investment allocations.

About the Author:

Don Carpenter is clinical professor of accounting at Baylor University. Contact him at Don_Carpenter@baylor.edu.
  • Workforce Development

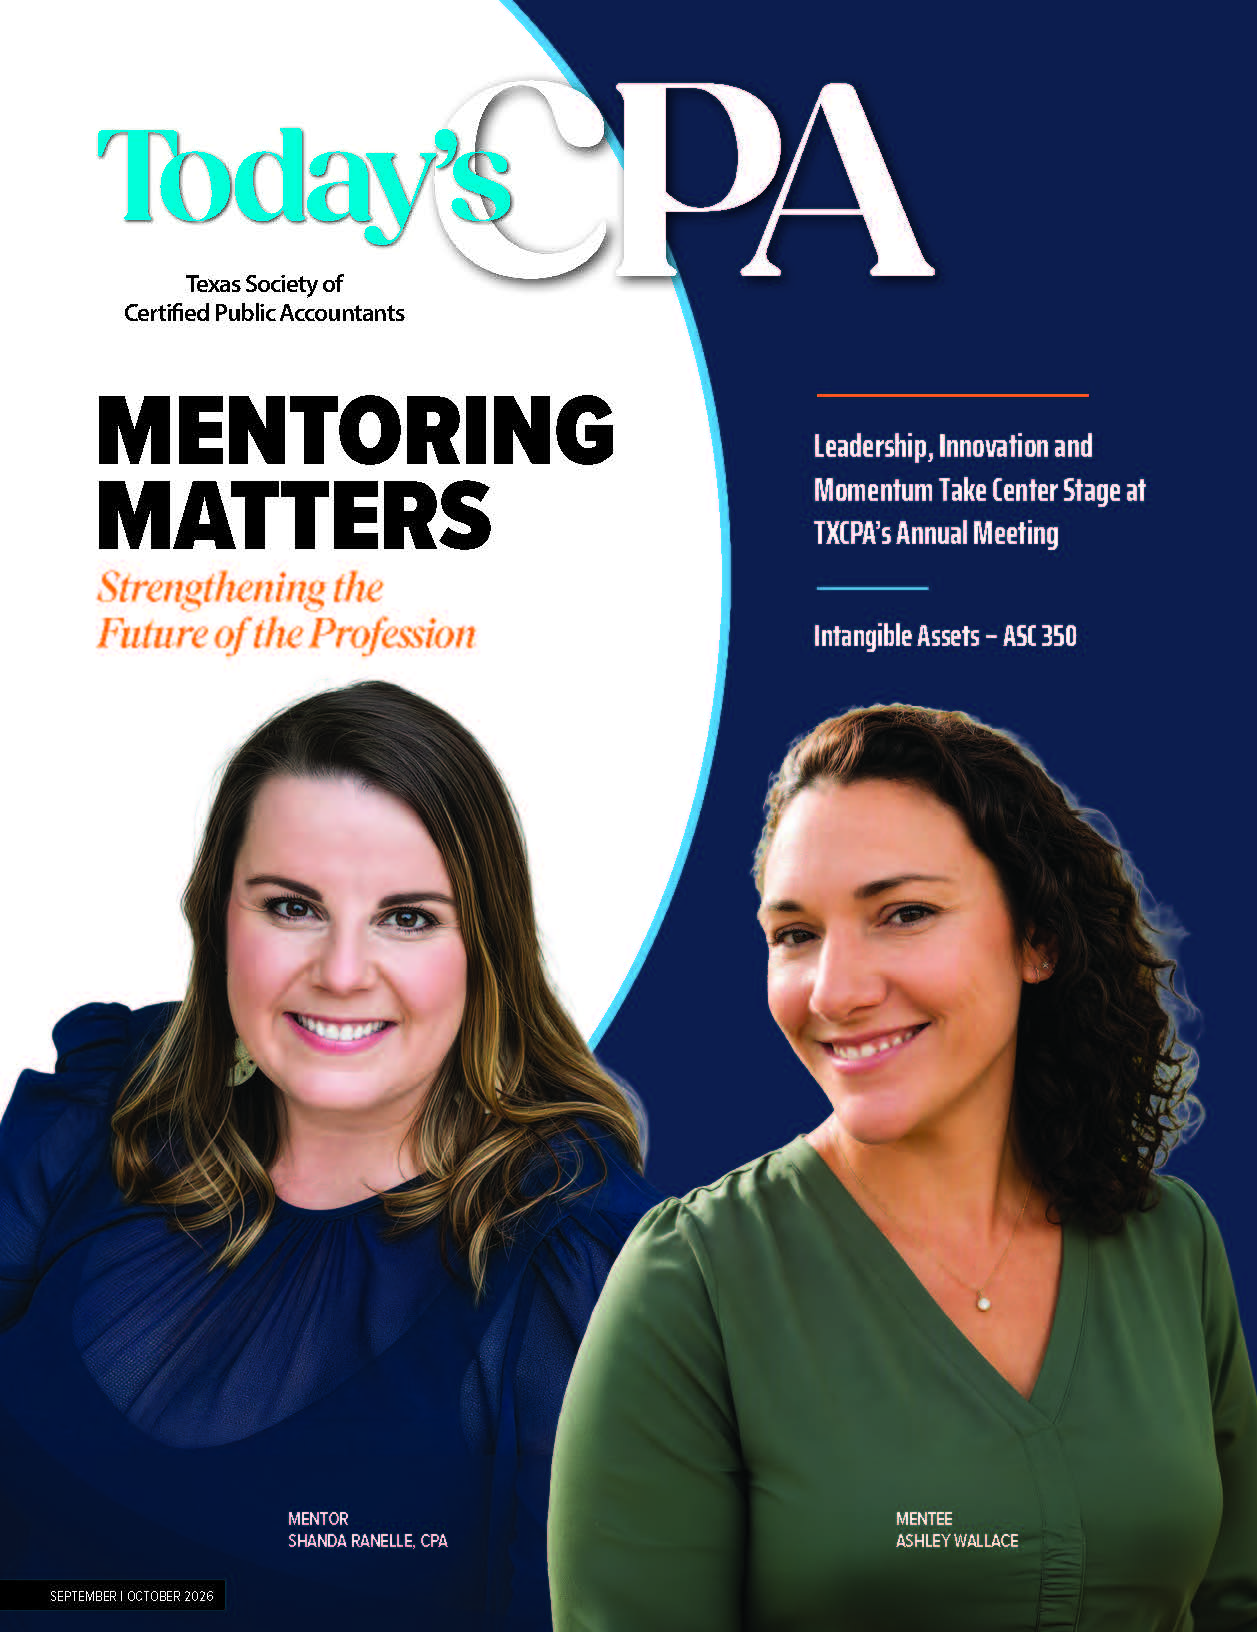
    Mentoring Matters: Strengthening the Future of the Profession

    Mentoring is a cornerstone of the accounting profession. From supporting students and CPA candidates to accelerating the growth of experienced professionals, mentoring strengthens confidence, preserves institutional knowledge and prepares future leaders. TXCPA's Mentor Match program is designed to help members build meaningful professional relationships that support their career growth and development.
    View Article
  • CPE: Intangible Assets – ASC 350

    FASB’s recent targeted GAAP improvements address the accounting and reporting of internally developed software. ASU 2025‑06 replaces development‑stage rules for internal‑use software with a “probable‑to‑complete” capitalization threshold.
    View Article
    IPR&D
  • volunteer leadership

    Leadership, Innovation and Momentum Take Center Stage at TXCPA's Annual Meeting

    TXCPA’s 2026 Annual Meeting brought more than 200 leaders together to celebrate organizational achievements, discuss emerging trends and shape the future of the organization. As the organization enters the final year of its Strategic Plan, the meeting emphasized momentum, collaboration and continued involvement in TXCPA and the accounting profession.
    View Article
  • Expanding the CPA Pipeline: An Important Joint Initiative for CPA Firms and K-12 Schools

    CPA firms, universities and professional organizations are using coordinated efforts to expand the future CPA talent pipeline by reaching students much earlier in the K‑12 system. Because many students choose career pathways as early as 8th grade, the authors emphasize shifting outreach toward freshmen and sophomores already inclined toward business studies.
    View Article
    TXCPA Accounting Opportunities Month
  • Workforce Development

    Mentorship, Momentum and the Future of the Profession

    Strong connections are essential to the future of the CPA profession. This CEO's Message highlights the power of mentorship, TXCPA’s efforts to strengthen the accounting pipeline, and the many ways members, volunteers and chapters are helping build opportunities for the next generation of CPAs.
    View Article
  • Outstanding Chapter Awards Recognize Achievements in Leadership and Service

    TXCPA’s Outstanding Chapter Awards recognize small and medium-sized chapters for excellence in leadership, member service, innovation and community involvement. The 2025-26 recipients, TXCPA Rio Grande Valley and TXCPA East Texas, were honored for their strong student outreach initiatives, professional development opportunities, scholarship fundraising, member engagement and community service.
    View Article
    volunteer leadership
  • Workforce Development

    Beyond Tax and Audit: Shedding Light on Alternative Career Pathways

    Accounting offers far more career opportunities than traditional tax, audit and financial reporting roles. By introducing students to the diverse ways accounting skills can be applied, educators and practitioners can help the next generation of CPAs see the many possibilities an accounting career can offer.
    View Article
  • What’s Happening Around Texas - September-October 2026

    TXCPA chapters across Texas are strengthening connections through student engagement events, legislative conversations, member appreciation gatherings, and strategic planning sessions. From Corpus Christi’s student bowling mixer and to Southeast Texas’ celebration with Lamar University to El Paso's and San Antonio’s focused planning meetings and Victoria’s community‑building event, each chapter is fostering momentum, collaboration and professional growth.
    View Article
    TXCPA Chapters
  • Tenure

    Is Accounting Academia Still a Good Career Option for CPAs? An Updated Perspective

    Is accounting academia still an attractive career path for CPAs? Although demand for accounting Ph.D. graduates has declined despite earlier predictions of faculty shortages, accounting professors continue to enjoy strong compensation, work/life balance, tenure stability and summer flexibility.
    View Article
  • Spotlight Article: Leading Beyond the Numbers

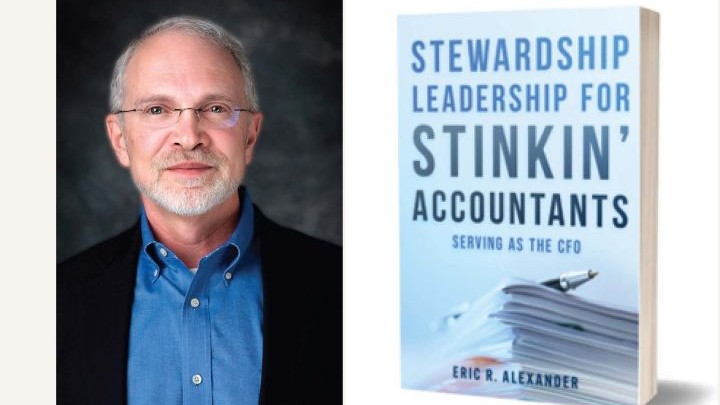
    Eric R. Alexander discusses the lessons behind his book “Stewardship Leadership for Stinkin' Accountants: Serving as the CFO” and how a servant mindset, wisdom and relationships create a lasting impact. He explores why trust, accountability and communication are essential to effective financial leadership, especially as AI transforms the profession.
    View Article
    Strategic Planning
  • Sustainability reporting

    Assessing Materiality of ESG Risks: Guidance for CPAs

    This article explains how CPAs can assess and disclose material environmental, social and governance (ESG) risks that may affect a company’s financial position, operations and stakeholders. The concept of double materiality is introduced, which considers both the financial impact of ESG risks on a company and the company’s impact on society and the environment.
    View Article
  • PCC Addresses Priority Private Company Issues in Q2

    This update summarizes the Private Company Council (PCC) activities for the second quarter of 2026. During its June meeting, the council prioritized improving financial disclosures for Employee Stock Ownership Plans (ESOPs) and targeted lease accounting simplifications for private companies, and discussed FASB's decision to add a project on subjective acceleration clauses and debt default disclosures.
    View Article
    Private Company Council
  • volunteer leadership

    Leading the Way: TXCPA Thanks Our 2026-2027 Faculty and Student Ambassadors

    TXCPA celebrates and thanks our 2026–2027 Faculty and Student Ambassadors, whose leadership and enthusiasm bring our programs, resources and opportunities directly to campuses across Texas. Their commitment strengthens our connection to future professionals and fuels the growth of the CPA pipeline statewide.
    View Article
  • Profitable Is Not the Same as Valuable

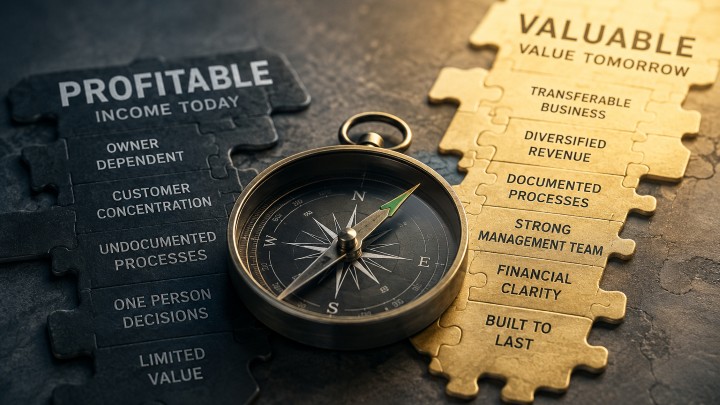
    A profitable business is not necessarily a valuable or transferable one, as enterprise value depends on organizational architecture rather than dependence on the owner’s involvement. The central message: profitable operations generate income, but only well‑structured businesses build equity that can be sold, transferred or relied upon for retirement.
    View Article
    valuation
  • Workforce Development

    A New Era for CPA Licensure in Texas – and a Look Ahead

    Texas has entered a new phase of CPA licensure with the implementation of Senate Bill 262 on August 1, 2026, creating an alternative pathway that allows candidates to qualify with 120 hours of education and two years of experience, alongside the traditional 150‑hour route. As the 2027 legislative session approaches, TXCPA is preparing to protect strong licensing standards, monitor deregulation efforts and engage newly elected lawmakers.
    View Article
  • Take Note

    In this edition of Take Note: A Legacy of Mentorship - A Tribute to John Baines, CPA-Dallas; Accountants Confidential Assistance Network (ACAN); CGMA® Designation; TXCPA Member Insurance
    View Article
    TXCPA Member Insurance
  • Virtual Accounting

    Classifieds

    The Classifieds section of Today's CPA provides a one-stop destination to find practices for sale, connect with buyers, and access services that support growth, transition and market expansion.
    View Article
  • Download Full September-October 2026 Issue (PDF)

    View Article


CHAIR
Angela Ragan, CPA

PRESIDENT/CEO
Jodi Ann Ray, CAE, CCE, IOM

CHIEF OPERATING OFFICER
Melinda Bentley, CAE

EDITORIAL BOARD CHAIR
Derrick Bonyuet-Lee CPA, CGMA

MANAGER, MARKETING AND COMMUNICATIONS
Peggy Foley
pfoley@tx.cpa

MANAGING EDITOR
DeLynn Deakins
ddeakins@tx.cpa

CLASSIFIEDS
DeLynn Deakins
ddeakins@tx.cpa

Texas Society of CPAs
14131 Midway Rd., Suite 850
Addison, TX 75001
972-687-8550


EDITORIAL BOARD
Derrick Bonyuet-Lee, CPA-Austin;
Drew Chumley, CPA-Fort Worth;
Adam Dimmick, CPA-Houston;
Julia Frink, CPA-Fort Worth;
Baria Jaroudi, CPA-Houston;
Jeffrey Johanns, CPA-Austin;
Brian Johnson, CPA-Central Texas;
Michael Kraten, CPA-Houston;
Lucas LaChance, CPA-Dallas;
Shilpa Boggram Sathyamurthy, CPA-Houston.

CONTRIBUTORS
Melinda Bentley; Kenneth Besserman; Holly McCauley; Shicoyia Morgan; Craig Nauta; Triniti Patterson


10:00 Acting as Manage