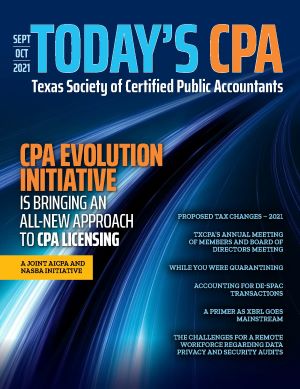
CPA Evolution Initiative is Bringing an All-New Approach to CPA Licensing
Major changes are underway that are transforming the CPA licensure model. The CPA Evolution initiative is bringing an all-new approach to licensing based on a critical purpose: meet the continuing demand for the skills and competencies required by the accounting profession today and into the future.
The CPA Evolution initiative is a joint project of the National Association of State Boards of Accountancy (NASBA) and the American Institute of CPAs (AICPA). It will put in place a flexible and adaptable licensure approach that will serve as the foundation for future-proofing the CPA profession.
Over three years, NASBA and AICPA gathered input from more than 3,000 stakeholders from across the profession, including representatives from state boards of accountancy, academia, students, firms of all sizes, and state CPA societies. During these conversations, several key themes became clear:
- The profession supports the need to change the CPA licensure model;
- Newly licensed CPAs should all demonstrate strong common core competencies;
- The new CPA licensure model should position the CPA for the future; and
- The new CPA licensure model should continue to protect the public interest.
Based on this feedback and lessons learned from studying other international and domestic licensure models, NASBA and AICPA developed the new approach. The initiative was approved by the AICPA Governing Council and the NASBA Board of Directors in 2020.
The New CPA Licensure Model
The new model takes a Core + Discipline approach, starting with a deep and strong Core in accounting, auditing and tax with technology woven throughout that all candidates will complete. The sections will comprise content that every newly licensed CPA may be exposed to in practice and assess the knowledge and skills critical to protecting the public interest.
Each candidate will also choose a Discipline in which to demonstrate deeper skills and knowledge. There will be three Discipline sections from which candidates must choose and pass one. The proposed sections are:
- Business Accounting and Reporting (BAR);
- Information Systems and Controls (ISC); and
- Tax Compliance and Planning (TCP).
The topics covered in these sections apply to newly licensed CPAs who work in these areas of practice and are less likely to be encountered by CPAs who are not focused on that area of practice.
Regardless of the chosen Discipline, this model leads to full CPA licensure, with rights and privileges consistent with any other CPA. A Discipline selected for testing will not mean the CPA is limited to that practice area.
What do the changes mean for the Uniform CPA Exam? The specific content of the Core and the Disciplines will be determined by a CPA Exam practice analysis, which is happening now. Practice analyses – gathering information about the current and future state of the profession and the work of newly licensed CPAs – are conducted periodically as part of AICPA’s ongoing efforts to make sure the Exam is current and to maintain its validity and reliability.
During the practice analysis, AICPA will engage with subject matter experts and other stakeholders to determine the appropriate content to be assessed in the Core and Discipline sections. Information and progress will be shared periodically and requests will be made for public input.
The current practice analysis will likely wrap up in 2022 and an Exam Blueprint will be exposed for public comment in mid-2022. AICPA and NASBA expect the new Exam will launch in January 2024. All practice analysis questions can be directed to the AICPA Examinations team at PracticeAnalysis@aicpa.org.
During the early stages of the CPA Evolution Initiative, an analysis was performed that identified eight jurisdictions, including Texas, that would require their board of accountancy to amend their statutes or rules because the statutes or rules referred to existing Uniform CPA Examination section names. It is anticipated that the eight jurisdictions will complete the necessary amendments before the launch of the new Exam in January 2024.
The Texas State Board of Public Accountancy has determined that the Uniform CPA Exam Blueprints defined by AICPA are the guide for accounting course requirements. Board Rule 511.57 provides the requirements and accounting courses that may be taken. The State Board has sent out a survey to accounting departments asking for their readiness for curriculum changes.
The new CPA licensure model will strengthen the State Board public protection mandate and can be adapted over time as the role of the CPA continues to evolve.
Impact on Educators and Accounting Academic Programs
Accounting educators will play a vital role in preparing students to pursue the CPA license under this new model. AICPA’s and NASBA’s CPA Evolution Model Curriculum was developed to assist faculty who want to prepare their students for the CPA profession.
The CPA Evolution Model Curriculum is materially aligned with the Uniform Accountancy Act Model Rules for education and reflects insights gathered through the 2021 CPA Exam Practice Analysis, as well as the views of subject matter experts who served on the CPA Evolution Model Curriculum Task Forces.
The Task Forces were comprised of more than 40 volunteers, including faculty from small schools and large universities, CPAs in public practice, business and industry, and representatives from state boards of accountancy. The Task Forces met over 50 times over the course of six months.
View the CPA Evolution Model Curriculum guide for accounting educators.
Faculty can also access the Academic Resource Hub, a database of content from AICPA, accounting firms, academics and AICPA teaching-award winners that will help faculty prepare students for the rapidly evolving demands of the profession. The hub contains over 200 resources for a range of class levels on topics like data analytics and cybersecurity to use in classroom instruction, research or guidance.
New resources will continue to be added and the ARH is free for faculty to access. It simply requires an login on This Way to CPA (no AICPA membership required).
Throughout 2021, AICPA will also be holding a series of Faculty Hour webinars for accounting educators. This free monthly webinar series includes regular updates on CPA Evolution and deep dives into emerging topics to include in accounting courses. Register for upcoming webinars and watch recordings of the past sessions.
The new CPA licensure model uses a Core + Discipline approach. It starts with a deep and strong Core in accounting, auditing, tax and technology that all candidates will be required to complete. Each candidate will also choose a Discipline in which to demonstrate deeper skills and knowledge.
Impact on Students and CPA Candidates
Aspiring CPAs who are college freshmen now will be among the first to take the overhauled version of the CPA Exam when it launches in 2024. Current CPA candidates will be able to sit for the current CPA Exam until the launch of the new Exam, and a transition plan is being developed for candidates who have started but not completed the CPA Exam process as of January 2024.
What areas of the CPA Exam will remain the same? Candidates will still be tested at the one- to two-year level. The Exam will be no longer than 16 hours, just like today, and there will be no new experience requirements to sit for the Exam.
Candidates will still be required to pass a total of four Exam sections and those sections can be taken in any order. This means, for example, a candidate could take the Tax Core and follow that up with the Tax Discipline before passing the rest of the Core.
There will be no separate time limits to pass the Core and the Discipline. Candidates will have one set amount of time to pass, just like today.
How might the Exam change? While much of the Exam would stay the same, changes are required to integrate the Disciplines. Candidates will be required to pass the three Core sections and one Discipline section as discussed above. They will not be permitted to pass additional Disciplines – once they pass one, their Discipline requirement will be complete. Each section of the new Exam will cover discrete content and a range of skills.
Last, and importantly, the Discipline the candidate passes will not differentiate the license granted. The new Exam is expected to launch in January 2024.
AICPA’s New CPA Evolution Resource Competition!
In August, AICPA announced the new CPA Evolution Resource Competition (CERC). The competition seeks to promote the development of teaching resources for the new topics and learning objectives outlined in the CPA Evolution Model Curriculum.
AICPA invites accounting faculty to submit their original long or short teaching cases, exercises or other instructional materials to be considered for a CERC award of $300 - $1,500. Submissions can range from case studies to course exercises to general instructional materials that serve as teaching resources for new topics and learning objectives outlined in the model curriculum.
The deadline to apply as an individual or as a team is October 31, 2021. For all the details, visit the CPA Evolution Resource Competition (CERC) site.
Impact on Employers
AICPA and NASBA surveyed the top 100 accounting firms and the results showed there are significant gaps between what practice is demanding and what students are learning in accounting programs, especially when it comes to systems, data analytics, cybersecurity and IT audit. Research also confirmed that much more technology continues to shape the work of all CPAs, year after year.
Employers expect graduates to enter the workforce already familiar with various technologies and able to examine data critically. Procedures historically performed by newly licensed CPAs are being automated, offshored or performed by paraprofessionals.
Entry-level CPAs are performing more procedures that require deeper critical thinking, problem-solving and professional judgment. Responsibilities that were traditionally assigned to more experienced staff are being pushed down to the staff level.
If graduates coming out of accounting programs don’t have the necessary skills, the firms must look elsewhere for this talent. A recent AICPA Trends Report showed that from 2014 through 2018, firms were hiring 29% fewer accounting graduates. Some firms have taken steps to develop partnerships with universities to address the potential lag between college learning and the requirements of professional life.
Changes are needed to address the gaps in the skills employers require of their employees and the curriculum newly licensed CPAs are learning. The CPA Evolution initiative is being developed to help address these gaps.
The Future is Taking Shape
We are in an unprecedented time of change for the accounting profession. The CPA Evolution initiative and new licensure model are designed to equip newly licensed CPAs with the skills and competencies required as the practice of accountancy continues to evolve. They’re designed to meet the needs of employers and position the accounting profession as a valuable option for students choosing their career paths.
As the CPA Evolution initiative continues to progress, please check for updates at EvolutionofCPA.org. If you have any questions, please reach out to Feedback@EvolutionofCPA.org.
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
Watch CPA Evolution Videos on YouTube
New CPA Exam Changes - CPA Exam Evolution of 2024
CPA Evolution: The Opportunity for Educators
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
Highlights of the New Licensure Model
The new licensure model:
• Enhances public protection by producing candidates who have the deep knowledge necessary to perform high-quality work, meeting the needs of organizations, firms and the public;
- Is responsive to feedback, as it builds accounting, auditing, tax and technology knowledge requirements into a robust common Core;
- Reflects the realities of practice, requiring deeper proven knowledge in one of three Disciplines that are pillars of the profession;
- Is adaptive and flexible, helping to future-proof the CPA as the profession continues to evolve;
- Is not expected to change the number of sections in the CPA Exam or increase the length of the Exam; and
- Results in one CPA license.
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
Required Skills and Knowledge
Areas requiring deeper skills and knowledge for newly licensed CPAs include:
- Critical thinking;
- Professional judgment;
- Problem-solving;
- Understanding systems, controls and risk;
- Data management and analysis; and
- Performance of System and Organization Controls (SOC) engagements.
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
Sources:
AICPA
NASBA
Journal of Accountancy
AICPA Insights
TSBPA
Special thanks to Daniel Dustin, CPA; Vice President, State Board Relations; NASBA; and Tracie Miller-Nobles, Ph.D., CPA-Austin; Associate Professor; Austin College.