May 08, 2026
CPE: Option-Based Contracts and Foreign Currency Transactions
By Josef Rashty
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
CPE Self Study Article & Quiz Register to gain access to the self-study quiz and earn one hour of continuing professional education credit by passing the quiz.
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
CPE Hours: 1
Curriculum: Accounting and Auditing, Tax
Level: Basic
Designed For: CPAs in business and industry and public practice
Objectives: To address the accounting implications of option contracts utilized in foreign currency transactions and describe forward and futures contracts
Key Topics: Derivative instruments; underlying; notional amount; option-based contracts; call options; put options; net settlement; premium; time value; and forward and future-based contracts
Prerequisites: None
Advanced Preparation: None
~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~ ~~
Derivatives are financial instruments or other contracts that exhibit characteristics such that their fair values are dependent on one or more underlyings. An underlying may be an interest rate, price, foreign exchange rate, index, or other variable. For example, the fair value of an interest rate swap changes in response to movements in an interest rate index such as the Secured Overnight Financing Rate (SOFR). Other common underlyings include foreign currencies, investment securities and commodities.
Derivatives used in practice generally fall within two categories: contracts that require or permit settlement on a forward or future basis and contracts that provide the holder with optionality over whether settlement will occur. This article addresses the accounting implications of option contracts utilized in foreign currency (FX) transactions and, for context, includes a brief description of forward and futures contracts to distinguish their contractual characteristics from those of option-based arrangements.
Option-based contracts qualify as derivatives because their fair values are determined by reference to an underlying, such as a foreign currency exchange rate. These contracts convey to the holder a contractual right - but not an obligation - to cause the purchase or sale of the underlying at a specified price during a defined exercise period or on a stated expiration date.
Derivative Instruments
ASC 815, Derivatives and Hedging, describes a derivative instrument as a financial instrument or other contract that satisfies certain defining features. Specifically, it must include (1) an underlying variable, (2) a notional amount or a provision that determines the settlement, and (3) contractual terms that specify how payments or settlements are calculated based on the interaction of the underlying and the notional amount.
A derivative contract contains one or more underlyings and one or more notional amounts or payment provisions, or both. It requires no initial net investment or only a minimal one that is smaller than would be required for other contracts with similar responses to market changes. The terms of the derivative specify the settlement amount, which, if settlement occurs, is determined by changes in the underlying.
These features distinguish derivatives from other financial contracts because the value of a derivative is derived from the behavior of an underlying variable such as interest rates, foreign currency exchange rates, commodity prices, or equity prices rather than from ownership of the underlying asset itself. Consequently, derivatives enable entities to manage or transfer exposures to financial risks in a targeted and economically efficient manner.
Option-Based Contracts
Option-based contracts (options) require the sellers (writers) to fulfill their contractual obligations if the purchasers (holders) elect to exercise the options. The mechanism for executing such a transaction is typically a call option, under which the purchaser pays a premium to the seller to obtain the right, but not the obligation, to purchase the underlying asset at a predetermined price.
Option-based contracts are generally not considered hedge instruments (the two scenarios of the illustration in this article clarify that). For instance, in a cash flow forward exchange rate hedge, the seller locks in a specific exchange rate1 for a future currency transaction to protect against unfavorable foreign currency fluctuations. Entities employ such strategies to mitigate risk and provide predictability for future cash flows. However, this approach also eliminates the potential benefit of favorable exchange rate movements, which aligns with the primary objective of a hedge to reduce variability rather than to speculate.
Call Option
A call option gives the holder the right, but not the obligation, to buy an asset at a specified price (the strike price or exercise price) on or before a specified maturity date (expiration date). For example, the holder of a call option may have the right to purchase a commodity at a specified price (exercise price) within the next three months.
A call option meets the definition of a derivative instrument if it (1) has an underlying and a notional amount, (2) requires little or no initial net investment, and (3) can be settled at a future date. Suppose a company designates a call as a hedging instrument in a qualifying hedge relationship. In that case, it accounts for changes in its fair value in accordance with the type of hedge fair value hedge, cash flow hedge or net investment hedge as specified in ASC 815. However, if a call option does not qualify for hedge accounting, the company records all changes in the fair value of call options in earnings.
A call option is in the money when the price of the underlying asset is greater than the strike price (exercise price) of the option.
Put Option
A put option gives the holder the right, but not the obligation, to sell an asset at a specified price (the strike or exercise price) on or before a specified maturity date. For example, the holder of a put option may have the right to sell a commodity at the exercise price within the next three months.
A put option is in the money when the price of the underlying asset is lower than the strike price (exercise price) of the option.
Forward and Future-Based Contracts
Forward and futures contracts are derivative instruments in which two parties agree to buy or sell a specified asset at a predetermined price on a future date. By locking in prices in advance, both buyers and sellers can reduce their exposure to adverse price movements.
Forward contracts are customized, privately negotiated over-the-counter (OTC) market agreements tailored to specific quantities, dates and settlement terms, making them useful for hedging targeted exposures. Their bespoke nature also increases counterparty risk because no clearinghouse guarantees performance.
In contrast, futures contracts are standardized agreements traded on organized exchanges. The exchange specifies contract size, quality, delivery time, and settlement procedures, and a clearinghouse guarantees performance, thereby significantly reducing counterparty risk. Futures are marked to market daily and their standardized structure facilitates liquidity, price transparency and ease of trading.
Option contracts differ from both forwards and futures because the option holder is not obligated to transact; rather, they possess the right, but not the obligation, to buy or sell an underlying asset at a predetermined strike price. The maximum loss for an option buyer is limited to the premium paid. By contrast, futures contracts can expose traders to substantial losses because both parties are legally obligated to fulfill the contract regardless of market movements.
Terminologies
Underlying
An underlying is a variable that, together with either a notional amount or a payment provision, determines the settlement value of a derivative instrument. According to ASC 815-10-15-88, common examples of underlyings include the following:
- The price of a commodity or a commodity price index;
- An exchange rate or an interest rate index;
- The occurrence (or nonoccurrence) of a specified event.
Notional Amount
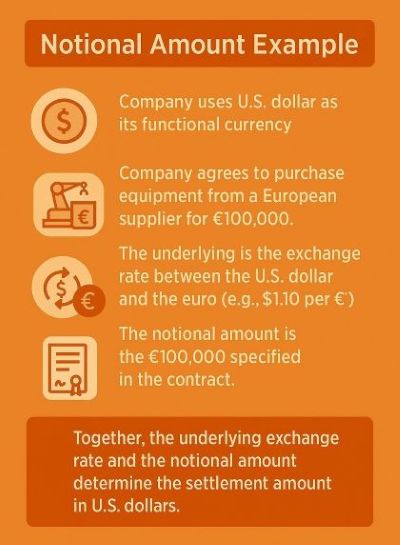
A notional amount refers to the units such as currency units, shares, bushels, or pounds specified in a derivative contract (ASC 815-10-15-92). It forms one side of the equation used to determine the settlement amount of a derivative. The settlement amount is derived from the interaction between the underlying and the notional amount. Following is an example.
Requirements Contract
A requirements contract is a derivative contract that meets the definition of a derivative under ASC 815-10-15-88. In such a contract, one party agrees to purchase all of its required quantity of an underlying asset exclusively from another party. The purchaser may buy only what it needs for its own operations and is prohibited from acquiring excess quantities for resale. Thus, the buyer commits to fulfilling all of its needs from the seller over the contract term (ASC 815-10-55-5).
To qualify as a derivative, a requirements contract must include a notional amount, consistent with ASC 815-10-55-5 through ASC 815-10-55-7. Entities should evaluate these contracts at each reporting date to determine whether they continue to meet the criteria for derivative accounting (ASC 815-10-15-103).
Net Settlement
Net settlement means that a company can settle a contract at maturity by exchanging cash rather than physically delivering the underlying asset (ASC 815-10-15-99). Net settlement may arise through the contract s explicit terms, as a result of nonperformance or default, or through an established market mechanism.
Premium
Options require an upfront cash payment (premium) to enter into the contract. This one-time payment gives the option holder the right, but not the obligation, to benefit from favorable price movements (upside but not the downside). If the option is in the money, the holder will generally exercise it; if it is out of the money, the holder typically allows it to expire. In contrast, the option writer receives the premium as compensation for assuming the risk of potential adverse price movements inherent in the contract.
Time Value
Time value is the portion of an option s premium that exceeds its intrinsic value prior to expiration. It represents the amount an investor is willing to pay above intrinsic value in anticipation that the option may gain value before it expires. Time value reflects the possibility that the underlying asset s price will move favorably and generally increases with the length of time remaining until expiration. The accounting literature often refers to time value as extrinsic value because factors such as volatility, interest rates and time remaining influence it.
Illustration
First Scenario
Entity A anticipates a probable sale to a German customer and has the euro as its functional currency. To hedge the foreign-currency risk associated with the forecasted sale, Entity A enters into a put option that grants it the right to sell 100,000 in six months. On January 1, 20X1 and when the spot exchange rate is 1 = $1.10 Entity A purchases a put option that allows it to sell 100,000 for $115,000, reflecting a strike price of $1.15 per euro.
Entity A excludes from its hedge-effectiveness assessment all changes in the option s fair value other than intrinsic value, because the critical terms of the option are aligned with those of the forecasted transaction. Accordingly, changes in the option s intrinsic value are expected to offset the variability in the forecasted cash flows attributable to the risk of the U.S. dollar strengthening. Entity A designates the option as a hedge of a probable forecasted transaction and measures its fair value using the Black-Scholes-Merton model.
The hedge is effective if the U.S. dollar strengthens to $1.00 per 1.15 or further; it becomes ineffective if the dollar does not reach that level. Because Entity A s exposure is one-sided, the option structure also preserves the upside potential should the dollar weaken, an economic benefit that a cash-flow hedge using a forward contract cannot provide. In this illustration, the critical terms of the option match those of the anticipated transaction, including the currency, notional amount and timing. The key assumptions are summarized in Table 1. Table 2 reflects the calculation of spot intrinsic value of option-contract. Table 3 reflects the journal entries of this transaction.
Table 1. Key Assumptions and Fair Value of the Option
| Beginning of the Period | Spot Rate (EUR/USD) | Option Strike Price (EUR/USD) | Option Fair Value* |
| First Quarter (1/1/20X1) | 1.10 | 1.15 | $3,100 |
| Second Quarter (4/1/20X1) | 1.14 | 1.15 | $2,500 |
| Third Quarter (7/1/20X1) | 1.30 | 1.15 | $10,033 |
| * Fair values are based on the Black-Scholes-Merton option-pricing model. |
In Table 1 above, Entity A excludes from its hedge-effectiveness assessment all changes in the option s fair value other than intrinsic value (for example, time value). However, consistent with ASC 815-20-25-83A, Entity A amortizes the initial fair value of the excluded component ($3,100) and recognizes that time value systematically over the hedge period. Accordingly, only changes in the option s intrinsic value, measured using the option s spot-rate intrinsic value, serve as the basis for evaluating hedge effectiveness.
Table 2. Option Intrinsic Value, Time Value and Total Fair Value
| Period / Date | Intrinsic ( Spot ) Value of Option (1)(2) | Time Value of Option (3) | Total Fair Value of Option (4) |
| First Quarter 1/1/20X1 | $0 | $3,100 | $3,100 |
| Second Quarter 4/1/20X2 | $763 | $2,337 | $2,500 |
| Third Quarter 7/1/20X3 | $10,033 | $0 | $10,033 |
In Table 2 above:
1. Intrinsic value at 4/1/20X2: (" " 100,000/1.14) less" " (" " 100,000/1.15) $87,719 less $86,957 = $763
2. Intrinsic value at 7/1/20X3:(" " 100,000/1.30) "less " (" " 100,000/1.15) $76,942 less $86,957 = ($10,033)
3. Time value at 4/1/20X2: $3,100 initial fair value less $763 intrinsic value = $2,337
4. Entity A uses Black-Scholes-Merton valuation model to calculate the fair value of options.
Table 3. Journal Entries
| Periods/Dates | Purchased Option | Cash | Revenue | Other Comprehensive Income (OCI) | |||
| First Quarter | 1/1/20X1 | (1) | Beginning of the first quarter | $3,100 | ($3,100) | - | |
| 3/31/20X1 | (2) | End of the first quarter | ($600) | $1,500 | ($950) | ||
| Third Quarter | 6/30/20X1 | (3) | Second quarter | $7,533 | $1,500 | ($9,083) | |
| (4) | ($10,033) | 10,033 | - | ||||
| (5) | $130,000 | ($130,000) | |||||
| (6) | ($10,033) | 10,033 | |||||
| Total | - | $136,933 | ($136,933) | - |
In Table 3 above:
(1) $3,100 reflects the cost incurred to purchase the put option-contract.
(2) $1,550 reflects three-month straight-line amortization of the six-month option contract. ($600) reflects changes in the fair value of option from $3,100 to $2,500.
(3) 7,533 reflects changes in the fair value of option from $2,500 to $10,033. $1,550 reflects three-month straight-line amortization of the six-month option contract.
(4) $10,033 reflects the value of the option that Entity A has exercised and has received cash.
(5) To account for the sale transaction (" " 100,000 times 1.30)
(6) To reflect the value of the option in revenue upon its exercise.
In this illustration, Entity A had a windfall of $10,033 for the strengthening in Eur/USD conversion rate and a loss of $3,100 for the acquisition of put option contract.
Second Scenario
In the first scenario, the option was effective because the U.S. dollar strengthened to a rate above $1.00 to 1.15. However, in the second scenario, the U.S. dollar does not rise to that level. The assumptions for the first and second quarters' spot rates remain the same, but the third-quarter spot rate drops to $0.95. See Tables 4 and 5. Table 6 shows the journal entries.
Table 4. Key Assumptions and Fair Value of the Option
| Periods/Dates | Spot Rate Eur/USD | Option Strike Price Eur/USD | Option Fair Value |
| First Quarter Starting 1/1/20X1 | 1.10 | 1.15 | $ 3,100 |
| Second Quarter Starting 4/1/20X1 | 1.14 | 1.15 | $ 2,500 |
| Third Quarter Starting 7/1/20X1 | 0.95 | 1.15 | ($18,306) |
Table 5. Option Intrinsic Value, Time Value and Total Fair Value
| Periods/Dates | "Spot"/Intrinsic Value of Option (1) and (2) | Time Value of Option (3) | Fair Value of Option (4) |
| First Quarter Starting 1/1/20X1 | $ - | $3,100 | $3,100 |
| Second Quarter Starting 4/1/20X2 | $763 | $2,337 | $2,500 |
| Third Quarter Starting 7/1/20X3 | ($18,306) | $ - | (18,306) |
In Table 5 above:
(1) (" " 100,000/1.14) less (" " 100,000/1.15) [$87,719 less $86,957 = $763]
(2) (" " 100,000/0.95) less (" " 100,000/1.15) [$105,263 less $86,957 = $18,306]
(3) $3,100 less $763 = $2,337
(4) Entity A uses Black-Scholes-Merton valuation to calculate the fair value of the options.
Table 6. Journal Entries
| Periods/Dates | Purchased Option | Cash | Revenue | Other Comprehensive Income (OCI) |
| Beginning of the first quarter | $3,100 | ($3,100) | $ - | |
| End of the first quarter | ($600) | $1,550 | ($950) | |
| Second quarter | ($2,500) | $1,550 | $950 | |
| $95,000 | ($95,000) | |||
| Total | $91,900 | ($91,900) | $ - |
In the scenario above, the revenue declines to $95,000 (" " 100,000 times 0.95) and including the $3,100 option acquisition cost, the revenue total is $91,900, compared to $136,933 in the first scenario. Entity A does not exercise the acquired option, thereby limiting its loss to the option's acquisition cost ($3,100).
Latest Development
In September 2025, FASB issued ASU 2025-07, Derivatives and Hedging (Topic 815) and Revenue from Contracts with Customers (Topic 606). This ASU does not impact traditional market-standard put options. Nonetheless, companies need to evaluate each contract carefully for whether it meets the new scope exception (is non-exchange traded, underlying based on operations/activities of a party and not based on market rates/prices).
Summary
An option contract is a financial derivative that gives the holder the right, but not the obligation, to buy or sell an underlying asset at a predetermined price (called the strike price) before or on a specific expiration date. Practitioners often associate option contracts with equity-based underlying; however, companies can use option contracts in their foreign transactions to reduce the risk of FX fluctuations.
A put option contract is a financial derivative that gives the buyer the right, but not the obligation, to sell an underlying asset at a specified price within a specified period of time. On the other hand, a call option gives the right, but not the obligation, to purchase an underlying asset at a predetermined price before a set expiration date.
The article s illustration showed a put option, where a company sold to a buyer and received foreign currency. If instead the company had purchased goods from a foreign seller, it would have used a call option to hedge FX risk. In the first scenario, Entity A benefited when the U.S. dollar weakened against the euro but remained exposed when the dollar strengthened. A cash flow hedge using a forward contract, however, locks in a set exchange rate (e.g., EUR/USD 1.15) and protects against both dollar strength and weakness.
About the Author: Josef Rashty, CPA, Ph.D. (Candidate), is a member of the Texas Society of CPAs and provides consulting services in Silicon Valley, California. He is also a faculty and adjunct professor of accounting. Readers may reach him at j_rashty@yahoo.com for comments and suggestions.
Footnote
1. The current spot rate adjusted for the interest rate differential between the two currencies over the contract term derives the forward exchange rates.
Thanks to the Sponsors of Today's CPA Magazine
This content was made possible by the sponsors of this issue of Today's CPA Magazine: