March 05, 2026
The PCC’s Progress on Recent Agenda Priorities
By Jere Shawver, PCC Chair
I am pleased to have the opportunity to update TXCPA members on the activities of the Private Company Council (PCC) during the first quarter of 2026.
As many of you know, the PCC was established in 2012 by the Financial Accounting Foundation (FAF) to advise FASB on the appropriate accounting treatment for private companies for items under active consideration on FASB’s agenda. The PCC also advises FASB on possible alternatives within Generally Accepted Accounting Principles (GAAP) to address the needs of users of private company financial statements.
In addition to the update on recent activities, I will also highlight the PCC’s 2025 Annual Report, which was published earlier this spring.
March 2026 Meeting Update
At our most recent meeting in March 2026, the PCC discussed three current research projects – and added a fourth – that emerged from our structured process to evaluate our agenda priorities. These research projects address:
- Employee stock ownership plans (the newly added research project)
- Lease accounting simplifications
- Subjective acceleration clauses and related disclosures, and
- Debt modifications and extinguishments and troubled debt restructurings
Employee Stock Ownership Plans
PCC members discussed recent feedback from private company financial statement stakeholders (for example, lenders and sureties) during PCC liaison meetings and in response to the FASB 2025 Invitation to Comment, Agenda Consultation (2025 ITC), which primarily focused on repurchase obligations of employee stock ownership plans from a plan sponsor perspective.
PCC members added this topic as an area to research as part of their agenda priorities.
Lease Accounting Simplifications
In collaboration with the PCC’s leases working group, we are continuing our research to determine whether there are opportunities to further simplify the accounting guidance on leases for private company lessees.
PCC members discussed the key takeaways from the January 2026 leases working group meeting and recent stakeholder feedback. PCC members agreed with the following working group recommendations (all from a lessee perspective):
- Continue research on (a) lease modifications, (b) embedded leases, and (c) lease classification criteria
- In combination with other lease accounting issues (rather than as a standalone project), continue research on (a) weighted-average lease disclosures and (b) related party lease disclosures
- Discontinue research on (a) an optional single lease classification accounting model and (b) a scope exception for low value leases.
Subjective Acceleration Clauses and Related Debt Disclosures
Members discussed the FASB staff research on subjective acceleration clauses, which are prevalent in many private company debt arrangements and influence whether debt is classified as a current or noncurrent liability in a classified balance sheet. The PCC is exploring how to reduce the complexity in applying the guidance and more closely align it with lender practices.
PCC members recommended that FASB add a project to its technical agenda on subjective acceleration clauses in determining the classification of debt as a current or noncurrent liability in a classified balance sheet because the issue is not unique to private companies.
The PCC also recommended to FASB that the guidance be amended to:
- Remove the probability-based assessment guidance and instead, subjective acceleration clauses would affect the classification of debt only when triggered
- Describe a trigger as when a lender demands repayment of the underlying debt because of noncompliance with a subjective acceleration clause
- Require that long-term debt subject to a subjective acceleration clause be classified as a current liability when the subjective acceleration clause is triggered
- Make conforming changes to other areas of guidance that involve subjective acceleration clauses, such as the intent and ability to refinance guidance and revolving credit agreements
- Require certain disclosures when there is a trigger of a subjective acceleration clause
At a future meeting, FASB will discuss subjective acceleration clauses and related debt disclosures, including the PCC’s recommendations, for an agenda decision and initial deliberations.
Debt Modifications and Extinguishments and Troubled Debt Restructurings
The PCC is looking at certain areas in the debt modifications and extinguishments guidance that may warrant simplification for private companies.
PCC members discussed the key takeaways from the January 2026 debt modifications and extinguishments working group meeting. PCC members expressed concerns with the complexity of the current accounting models for debt restructurings and discussed recent feedback received in response to the 2025 ITC. PCC members acknowledged that FASB plans to discuss this topic at a future meeting and agreed to postpone further research on this topic until that meeting takes place.
Recent Town Hall and Liaison Meetings
PCC members discussed feedback received during the recent liaison meetings with:
- The Institute of Management Accountants (IMA) Small Business Shared Interest Group
- The Construction Financial Management Association (CFMA) Emerging Issues Committee
- Representatives of the surety industry through the National Association of Surety Bond Producers (NASBP) and The Surety and Fidelity Association of America (SFAA).
PCC members will hold a town hall-style forum at the AICPA ENGAGE Conference in June 2026. The next PCC meeting is scheduled for June 1-2, 2026.
The PCC 2025 Annual Report
The PCC recently published its 2025 Annual Report, which highlights the year’s accomplishments and activities. The PCC’s first Annual Report, which was published in March 2025, grew out of the FAF’s final report on the 2023-2024 Review of the Private Company Council.
The 2025 report includes: a message to private company stakeholders, 2025 highlights and key progress areas, a section on stakeholder engagement, a look at PCC agenda priorities, and a forward-looking strategy section. We encourage you to review the report and welcome any feedback or ideas for future annual reports.
Concluding Thoughts
If you have any private company financial reporting issues to raise with us or if you are interested in becoming more involved as either a PCC member or a PCC working group member, or providing feedback on FASB or PCC initiatives, please email us through the Contact Us portion of our webpage.
More information about our work is available by visiting our webpage at www.fasb.org/pcc and in the PCC's 2025 Annual Report.
We look forward to continuing to engage with TXCPA members over the course of 2026.
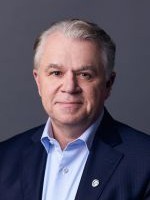
About the Author: Jere Shawver serves as Chair of the Private Company Council. He has over 40 years of experience advising companies on financial reporting, accounting and business matters, across a wide range of industries, including manufacturing and distribution, construction and real estate, higher education, hospitality, government contracting, and technology. He retired in May 2025 as Chief Executive Officer of Baker Tilly US, LLP, where he was responsible for managing the assurance practice and risk management, including the Office of the General Counsel.
The views expressed in this article are those of Mr. Shawver only. Official positions of the PCC and the FASB on accounting matters are determined only after extensive public due process and deliberation.
Thanks to the Sponsors of Today's CPA Magazine
This content was made possible by the sponsors of this issue of Today's CPA Magazine: